

FMA Alliance Ltd. Debt Settlement Letter From March 2008
This March 7, 2008 FMA Alliance letter identifies Bank of America as the creditor and records a $4,011.02 settlement agreement on a stated $10,027.54 balance. It schedules two payments, not one lump sum. The letter is evidence of the agreement, not proof that either payment cleared.
Check Your Debt Relief Options
No cost to check options. No obligation.
Prefer to talk now? Call 1-877-850-3328What This FMA Alliance Settlement Letter Documents
The letter is dated March 7, 2008. It names Bank of America as the creditor and states a balance of $10,027.54 as of January 8, 2008. Its $4,011.02 agreement amount is split into two scheduled payments of $2,005.51. The $6,016.52 difference is approximately 60% of the stated balance, before fees or possible taxes and conditional on the agreement being completed.
| Item | What This Letter Shows |
|---|---|
| Creditor Named In Letter | Bank of America |
| Collection Agency Named In Letter | FMA Alliance, Ltd. |
| Document Date | March 7, 2008 |
| Balance Stated In Letter | $10,027.54 |
| Agreement Amount In Letter | $4,011.02 |
| Scheduled Payments | $2,005.51 due March 31, 2008; $2,005.51 due April 30, 2008 |
| Potential Balance Reduction If Completed | Approximately 60%, before fees or possible taxes |
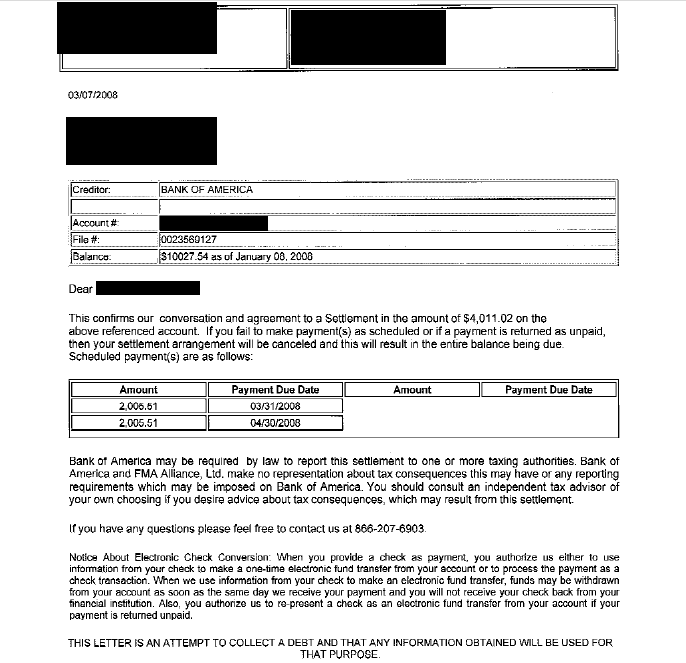
Historical agreement preserved in the CuraDebt archive. Identifying details are partly redacted; do not share account or reference numbers in public comments. See more settlement letters.
The approximately 60% reduction is calculated from the stated balance and agreement amount only. It is conditional on completion, is not proof of payment and does not include program fees or possible tax consequences.
How To Read This March 2008 Agreement
The schedule calls for $2,005.51 by March 31, 2008 and $2,005.51 by April 30, 2008. Together, those payments total $4,011.02. The letter says a missed scheduled payment or a payment returned unpaid cancels the arrangement and makes the entire balance due. These are historical terms for this account, not deadlines or instructions for paying a current debt.
The safest use of a historical example is to learn what should be documented. It should not be used to infer that the same creditor, a collector, or an independent provider will produce the same terms on another account.
A Verification Checklist For This Letter Type
Use the scanned document and the summary together. Before acting on a different agreement, verify each of the following in that agreement's own wording:
- The account number or reference is correct
- The settlement total equals the sum of required payments
- Due dates leave no ambiguity
- The document explains what completion resolves
- Personal information is stored securely after review
When an account has changed hands, confirm whether the sender is the original creditor, a servicer, a collection agency, or the current owner. That distinction can affect which records should be matched before payment.
Why A Written Agreement Matters More Than A Verbal Offer
A telephone conversation may start a negotiation, but it does not replace written terms. Before money is sent, the document should identify the account, the total required amount, payment dates, and the effect of completing those payments. Keep the agreement and proof of payment together.
For a current account, compare the full written terms with other available paths rather than choosing from a historical percentage alone. Compare debt relief options or review how a debt settlement program is structured.
A Step-By-Step Review Of This Archived Letter
1. Locate The FMA Alliance Account Reference
Match the creditor, collector and masked account details with records already in your possession. This letter identifies Bank of America as the creditor and FMA Alliance, Ltd. as the collection agency. Do not use an old letter or its contact details to verify a current payment request.
2. Reconcile $10,027.54 With $4,011.02
Check the stated balance against the settlement total. The account summary lists $10,027.54 and pairs it with $4,011.02. If installments appear in another offer, add them independently and confirm the sum matches the written total.
3. Find The Deadline Attached To The $4,011.02 Figure
An accepted amount is incomplete without timing. Check the scanned agreement for the payment date, schedule, and delivery instructions. Do not transfer the schedule from this old letter to a new account.
4. Identify The Completion Language Behind 60%
The document should make clear what happens after every required payment clears. That wording is more important than the percentage alone. For the page summary, 60% describes only the mathematical difference between $10,027.54 and $4,011.02.
5. Preserve Evidence From The March 2008 Record
Save the entire settlement document with transaction records and follow-up correspondence. An isolated payment receipt does not show the agreement. The archive page models a document-centered record.
6. Separate The Historical Result From A Current Decision
With the archived terms understood, evaluate current options on their own terms. A past agreement cannot establish current eligibility. Compare affordability, total cost, timing, account status, and credit priorities before choosing among repayment, consolidation, debt management, settlement, or another available route.
7. Use The FMA Alliance Letter As Evidence, Not A Promise
The scan supports a narrow conclusion: a written agreement specified an amount and payment schedule for one account. It does not prove that the scheduled payments cleared or that the account was resolved. Keep the agreement and any separate payment or completion records together.
Comparison Questions Raised By This Letter
Was The $4,011.02 Amount A Lump Sum Or Installments?
This agreement schedules two installments of $2,005.51, due March 31 and April 30, 2008. It is not a single $4,011.02 lump-sum payment. For a different offer, use its own dates, total and missed-payment terms.
Did FMA Alliance Or Another Account Holder Issue The Letter?
The letter names Bank of America as the creditor and refers to FMA Alliance, Ltd. as the collection agency. Those are different roles. For a current account, verify the present creditor, collector and payment instructions independently rather than relying on this 2008 example.
Does The 60% Figure Predict Credit Impact?
The balance reduction does not measure credit effects. Starting credit condition, account status, and subsequent updates can produce different outcomes. The 60% label on this page remains limited to the difference between $10,027.54 and $4,011.02.
Could The $10,027.54 Account Create A Tax Question?
Some canceled amounts may be relevant at tax time. This archive page cannot establish a person’s tax treatment. Keep later tax forms with the account file and use current IRS guidance.
How Should This March 2008 Example Be Used Today?
Let it illustrate what a paper trail can contain, without treating it as a present offer. Today’s choice requires current account information. The fact that the archived amount was $4,011.02 on a $10,027.54 balance does not set terms for another consumer.
What Makes This FMA Alliance Page More Than A Scanned Image?
The page pairs the original image with structured figures and definitions. It supports a careful review instead of asking the reader to infer every point from the scan. The unique combination here is FMA Alliance, March 2008, $10,027.54, $4,011.02, and 60%.
Frequently Asked Questions
What does this FMA Alliance settlement letter document?
It records a March 7, 2008 agreement for Bank of America debt handled by FMA Alliance, Ltd. The stated balance is $10,027.54 and the agreement schedules two $2,005.51 payments, totaling $4,011.02. The scan is not proof that either payment cleared. The approximately 60% difference is before fees or possible taxes and depends on completion.
Is this FMA Alliance letter a current offer?
No. The document is dated March 2008 and belongs to one archived account. It does not state what FMA Alliance or another account owner will offer today.
Is the 60% reduction net savings?
No. It compares the balance and settlement amount in this letter. It does not subtract program fees or account for possible tax consequences, so it should not be described as net savings.
How can I compare this FMA Alliance example with my account?
Use the document to identify terms that should be clear in writing, such as the account, total amount, due dates, and treatment of the remaining balance. Do not use its percentage as an estimate for a different account.
How long should settlement records be kept?
Keep the agreement, payment confirmations, and later account correspondence together. Retention needs can depend on the account and applicable law, so do not discard the documents immediately after payment.
What happens if an installment in a settlement agreement is missed?
Terms vary. This 2008 letter says a missed scheduled payment or a payment returned unpaid cancels the arrangement and makes the entire balance due. For a current account, read that agreement and obtain any changed terms in writing; do not assume the old letter controls a new account.
Should payment be sent before the agreement is in writing?
Written terms should be obtained and reviewed before payment. Confirm the sender, account, total amount, due dates, and treatment of the remaining balance, then keep the agreement with every payment record.
Does the percentage on this page show typical savings?
No. It is calculated only from the balance and settlement amount stated in this one archived letter. It is not a typical-result claim and does not include program fees or possible tax consequences.