

Citibank Debt Settlement Letter (October 2025): 60% Saved On A $3,078.78 Costco Visa Balance
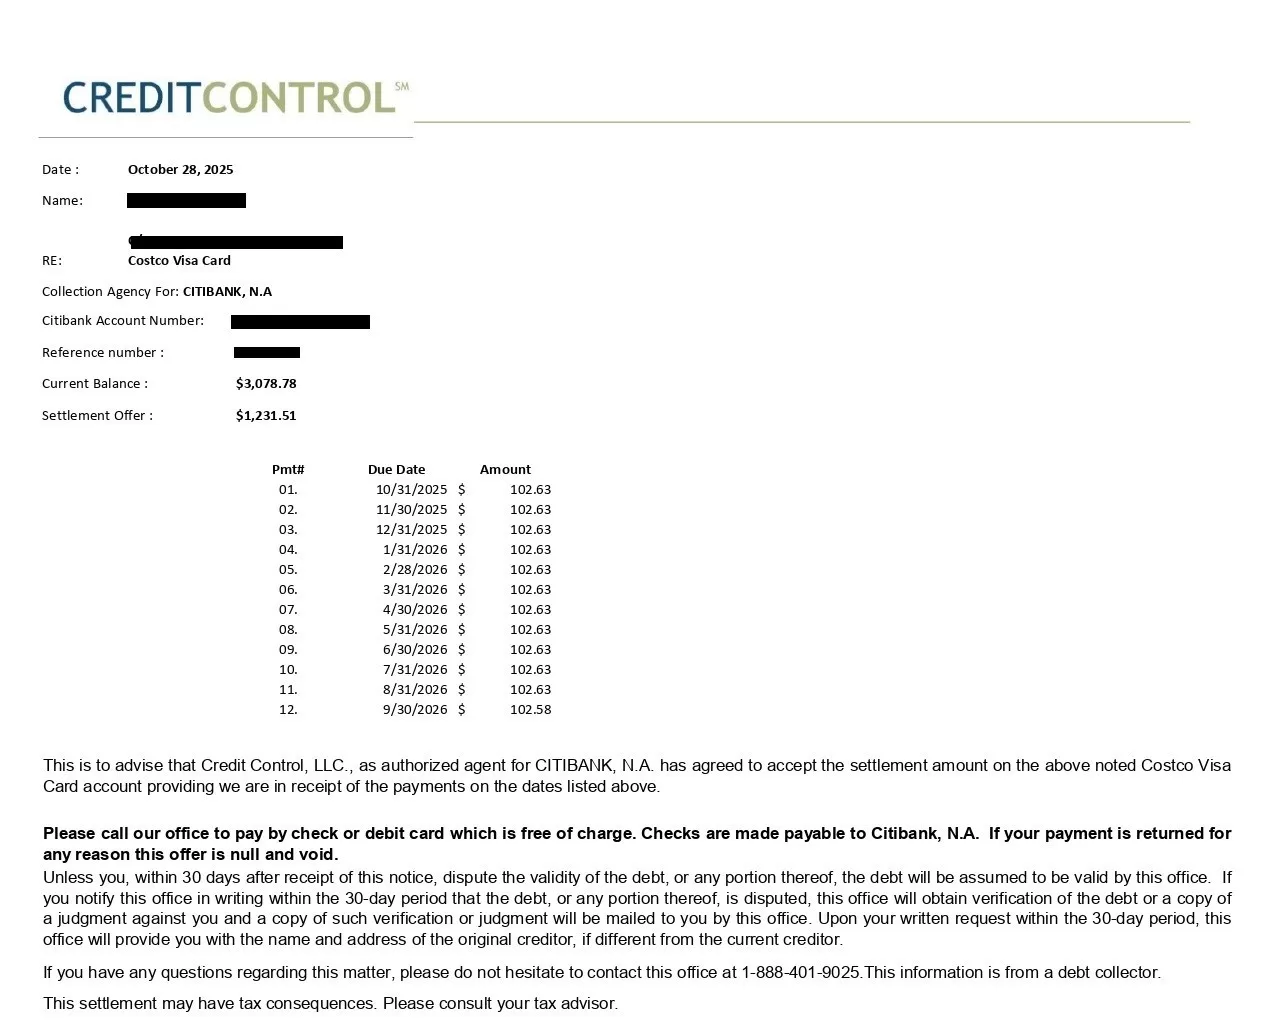
This October 28, 2025 letter shows Credit Control, LLC, acting for Citibank, N.A., agreeing to settle a $3,078.78 Costco Visa Card balance for $1,231.51. That is 40% of the balance, saving the client $1,847.27, or 60%, with 12 monthly payments of about $102.63. Results like this depend on the account and the client's situation and are not typical or guaranteed.
What Does This Settlement Letter Show?
This letter shows Credit Control, LLC, collecting for Citibank, N.A., agreeing to settle a $3,078.78 Costco Visa Card balance for $1,231.51, a savings of $1,847.27, or 60%. Here are the key terms from the letter:
| Detail | From the letter |
|---|---|
| Original creditor | Citibank, N.A. (Costco Visa Card) |
| Collection agency | Credit Control, LLC |
| Letter date | October 28, 2025 |
| Balance | $3,078.78 |
| Settlement amount | $1,231.51 (40% of the balance) |
| Amount saved | $1,847.27 (60%) |
| Payment terms | 12 monthly payments: 11 of $102.63 and a final payment of $102.58, from October 31, 2025 to September 30, 2026 |
Credit Control, LLC is a collection agency based in Hazelwood, Missouri that collects for original creditors and debt buyers. Here it acted as an authorized agent for Citibank, and the letter states that checks are payable to Citibank, N.A. The letter also includes the standard 30-day notice of the right to dispute the debt and warns that the offer is void if a payment is returned.
The Settlement Letter
Personal details are blacked out to protect the client's privacy.
How Does A Debt Settlement Like This Work?
Debt settlement is an agreement in which a creditor or collector accepts less than the full balance as payment in full. It is usually considered after someone has fallen behind and cannot realistically repay the whole amount. In a debt settlement program, the client sets aside money each month in a dedicated account, and offers are negotiated as funds build up. Settlements can be paid in one lump sum or, as in many letters, in a series of scheduled payments.
- No fee is charged until a debt is settled and the client has made a payment under the settlement.
- Accounts usually fall behind before they settle, which lowers credit scores and can lead to collection calls or lawsuits.
- Results depend on the creditor, the age of the account, the client's hardship and available funds. Not every account settles, and past results do not predict future results.
What Should A Settlement Letter Include?
Never pay a settlement until you have it in writing. A good settlement letter includes:
- The creditor or collector name and the account it covers
- The current balance and the agreed settlement amount
- Every payment amount and due date
- A statement that the account will be considered settled or resolved once payments are made
- How the account will be reported to the credit bureaus
See our debt settlement proposal letter template and checklist for more detail.
What Should You Know Before Settling A Debt?
- Credit impact. The account is typically reported as settled for less than the full balance, which can lower your scores. The negative history can remain for up to seven years from the first delinquency.
- Taxes. If $600 or more is forgiven, the creditor may send Form 1099-C, and the IRS may treat it as income unless you qualify for an exclusion such as insolvency (IRS Publication 4681).
- Your rights. You can ask a collector to validate a debt before you pay. See our guide to debt validation letters.
- Who you pay. When a collector works as an agent for the original creditor, the creditor may still own the debt. Confirm who receives payment, as this letter does by naming Citibank, N.A. as the payee.
Browse more examples in our debt settlement letters library, or compare all your choices at debt relief options compared.