

Sallie Mae Student Loan Settlement Letter From March 2015
This page preserves a dated Sallie Mae settlement letter so the written terms can be examined instead of guessed at. The image and figures below preserve the account-specific evidence while the surrounding guidance explains how to read it.
Check Your Debt Relief Options
No cost to check options. No obligation.
Prefer to talk now? Call 1-877-850-3328What This Sallie Mae Settlement Letter Documents
This archived record is dated March 2015. It identifies a balance of $14,607.28 and a settlement amount of $4,952.01. The difference between those two stated amounts is displayed as a 66% documented balance reduction.
| Item | What This Letter Shows |
|---|---|
| Creditor Or Account Name | Sallie Mae |
| Document Date | March 2015 |
| Balance Stated In Letter | $14,607.28 |
| Settlement Amount In Letter | $4,952.01 |
| Documented Balance Reduction | 66% |
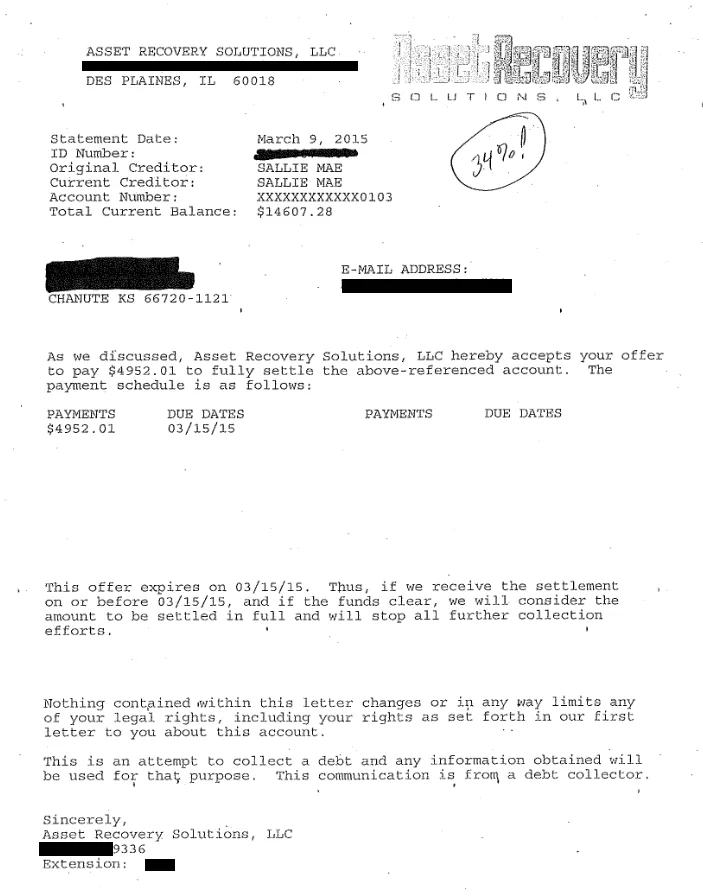
Historical settlement letter kept in the CuraDebt archive. Personal identifying details are redacted for privacy. See more settlement letters.
Calculated only from the balance and settlement amount shown in this letter. This is not net savings and does not include program fees or possible tax consequences.
How To Read This March 2015 Agreement
Start with the account reference and the party sending the letter. Then compare the stated balance of $14,607.28 with the agreed amount of $4,952.01. The 66% figure on this page is a calculation from those two numbers only; it is not a statement of net savings after fees or taxes.
The safest use of a historical example is to learn what should be documented. It should not be used to infer that the same creditor, a collector, or an independent provider will produce the same terms on another account.
A Verification Checklist For This Letter Type
Use the scanned document and the summary together. Before acting on a different agreement, verify each of the following in that agreement's own wording:
- The agreement concerns the intended account
- The amount accepted is not merely a temporary payment
- A missed-payment clause is reviewed if present
- The remaining-balance wording is clear
- Proof of each payment will be retained
When an account has changed hands, confirm whether the sender is the original creditor, a servicer, a collection agency, or the current owner. That distinction can affect which records should be matched before payment.
What A Settlement Confirmation Should Let You Prove
A useful confirmation should help establish which account was addressed, what amount was required, when it had to be paid, and how the remaining balance would be treated. The letter and the payment record should be retained together in case the account is later reported inconsistently.
For a current account, compare the full written terms with other available paths rather than choosing from a historical percentage alone. Compare debt relief options or review how a debt settlement program is structured.
Document Review Notes For This Specific Example
Using This Sallie Mae Record In A Broader Comparison
The archived image can demonstrate whether these particular terms existed with Sallie Mae. It does not determine the best current approach for another household. That comparison needs the person’s accounts, budget, credit goals, and available written terms.
A Paper Trail Built Around $14,607.28 And $4,952.01
The visual recap sets out $14,607.28 with $4,952.01 so the arithmetic is easy to follow. The complete document supplies the operative language. Let the recap guide the review without replacing the document.
Questions The March 2015 Letter Can And Cannot Resolve
The image may identify the creditor, balance, settlement figure, and stated conditions. It cannot establish a current creditor policy or reporting result. Check those open questions against current records.
Keeping The Sallie Mae Example Account-Specific
The three figures $14,607.28, $4,952.01, and 66% comes from the same dated record. Keeping them together keeps the evidence separate from predictions. For a second archived example, match the documents on more than percentage alone.
Reading The March 2015 Figures Together
For the document shown here Sallie Mae dates the account terms to March 2015. The balance appears as $14,607.28, with written terms totaling $4,952.01. Subtracting those figures produces $9,655.27; the displayed reduction is 66%.
What The $14,607.28 Balance Establishes
This opening figure $14,607.28 is specific to the document on this page. Readers should not treat it as a benchmark for another consumer. For a different account, verify the current record independently.
Why The $4,952.01 Amount Needs Written Context
The accepted amount shown as $4,952.01 can be evaluated because the document supplies context. An amount mentioned without a document leaves the essential conditions unconfirmed. Before acting on current terms, match the total to its deadlines and remaining-balance wording.
How To Interpret The 66% Label
On this record, 66% summarizes the gap between the stated figures. Readers should not convert it into an expected outcome for another account. A complete cost comparison requires costs beyond the two letter amounts.
A Step-By-Step Review Of This Archived Letter
1. Locate The Sallie Mae Account Reference
Begin by matching the institution name with the account details against a trusted statement. In the preserved example, the relevant creditor label is Sallie Mae and the document date is March 2015.
2. Reconcile $14,607.28 With $4,952.01
Check the stated balance against the settlement total. The scanned letter identifies $14,607.28 before showing $4,952.01. If installments appear in another offer, add them independently and confirm the sum matches the written total.
3. Find The Deadline Attached To The $4,952.01 Figure
An accepted amount is incomplete without timing. Look in the written terms for the deadline plus any installment sequence. A different account needs its own confirmed dates.
4. Identify The Completion Language Behind 66%
Look for wording that states the account consequence of paying the agreed total. That wording is more important than the percentage alone. For the page summary, 66% describes only the mathematical difference between $14,607.28 and $4,952.01.
5. Preserve Evidence From The March 2015 Record
Save the entire settlement document alongside payment evidence and later account notices. An isolated payment receipt does not show the agreement. The page keeps the account figures connected to their source.
6. Separate The Historical Result From A Current Decision
After the figures have been verified, return to the choices available now. This historical record does not forecast a new offer. Compare affordability, total cost, timing, account status, and credit priorities before choosing among repayment, consolidation, debt management, settlement, or another available route.
7. Use The Sallie Mae Letter As Evidence, Not A Promise
The strongest conclusion supported here is narrow: one account received the written terms displayed. It supplies no guarantee for a different balance. That distinction lets the page remain useful for research without presenting $14,607.28, $4,952.01, or 66% as a prediction.
Comparison Questions Raised By This Letter
Was The $4,952.01 Amount A Lump Sum Or Installments?
That cannot be decided from the summary card. Use the March 2015 letter to determine whether one or several payments were required. For a current comparison, compare the complete amount, the time allowed, and what occurs after a missed installment.
Did Sallie Mae Or Another Account Holder Issue The Letter?
The brand associated with a debt may differ from the current owner. Trace the party in the document through the available statements. Use the same ownership check for any present offer.
Does The 66% Figure Predict Credit Impact?
The balance reduction does not measure credit effects. Starting credit condition, account status, and subsequent updates can produce different outcomes. The 66% label on this page remains limited to the difference between $14,607.28 and $4,952.01.
Could The $14,607.28 Account Create A Tax Question?
Canceled debt can have tax consequences in some circumstances. The settlement document is not a substitute for tax guidance. Include any cancellation-of-debt form when obtaining account-specific tax advice.
How Should This March 2015 Example Be Used Today?
Use the archive to recognize important agreement fields, not as a price quote. Any new plan should be evaluated with up-to-date records. The fact that the archived amount was $4,952.01 on a $14,607.28 balance does not set terms for another consumer.
What Makes This Sallie Mae Page More Than A Scanned Image?
The summary connects the visual evidence to searchable account facts. It lets the image remain primary while making its key data easier to understand. The unique combination here is Sallie Mae, March 2015, $14,607.28, $4,952.01, and 66%.
Frequently Asked Questions
What does this Sallie Mae settlement letter document?
It records one historical account with a stated balance of $14,607.28 and a settlement amount of $4,952.01. The displayed 66% reduction is calculated from those two figures only.
Is this Sallie Mae letter a current offer?
No. The document is dated March 2015 and belongs to one archived account. It does not state what Sallie Mae or another account owner will offer today.
Is the 66% reduction net savings?
No. It compares the balance and settlement amount in this letter. It does not subtract program fees or account for possible tax consequences, so it should not be described as net savings.
How can I compare this Sallie Mae example with my account?
Use the document to identify terms that should be clear in writing, such as the account, total amount, due dates, and treatment of the remaining balance. Do not use its percentage as an estimate for a different account.
What should be checked after the final settlement payment?
Keep proof of payment and compare later account records with the written terms. If a balance or status appears inconsistent, use the agreement and receipts when requesting a review or correction.
Should payment be sent before the agreement is in writing?
Written terms should be obtained and reviewed before payment. Confirm the sender, account, total amount, due dates, and treatment of the remaining balance, then keep the agreement with every payment record.
Why are personal details removed from the displayed letter?
Names, addresses, and account details are redacted to protect privacy. The creditor name and financial terms needed to understand the historical example remain visible.
How long should settlement records be kept?
Keep the agreement, payment confirmations, and later account correspondence together. Retention needs can depend on the account and applicable law, so do not discard the documents immediately after payment.
