

Wells Fargo Financial Debt Settlement Letter
People searching for a Wells Fargo settlement example usually want proof of the amount, the date, and the promised account treatment. Those details are gathered here. The image and figures below preserve the account-specific evidence while the surrounding guidance explains how to read it.
Check Your Debt Relief Options
No cost to check options. No obligation.
Prefer to talk now? Call 1-877-850-3328What This Wells Fargo Settlement Letter Documents
This archived record is dated the date shown in the letter. It identifies a balance of $5,766.59 and a settlement amount of $1,200.00. The difference between those two stated amounts is displayed as a 79% documented balance reduction.
| Item | What This Letter Shows |
|---|---|
| Creditor Or Account Name | Wells Fargo |
| Document Date | the date shown in the letter |
| Balance Stated In Letter | $5,766.59 |
| Settlement Amount In Letter | $1,200.00 |
| Documented Balance Reduction | 79% |
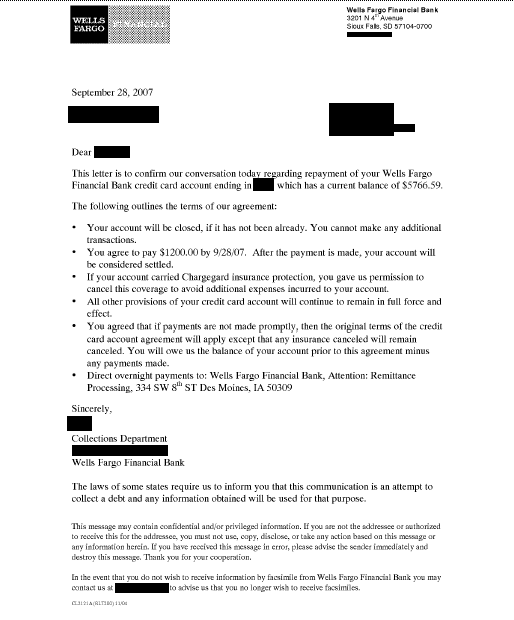
Historical settlement letter kept in the CuraDebt archive. Personal identifying details are redacted for privacy. See more settlement letters.
Calculated only from the balance and settlement amount shown in this letter. This is not net savings and does not include program fees or possible tax consequences.
How To Read This the date shown in the letter Agreement
The page summary makes the arithmetic easier to scan, while the letter image supplies the underlying evidence. Compare the image against the $5,766.59 balance, $1,200.00 agreed amount, and 79% documented reduction displayed below.
The safest use of a historical example is to learn what should be documented. It should not be used to infer that the same creditor, a collector, or an independent provider will produce the same terms on another account.
A Verification Checklist For This Letter Type
Use the scanned document and the summary together. Before acting on a different agreement, verify each of the following in that agreement's own wording:
- The agreement concerns the intended account
- The amount accepted is not merely a temporary payment
- A missed-payment clause is reviewed if present
- The remaining-balance wording is clear
- Proof of each payment will be retained
When an account has changed hands, confirm whether the sender is the original creditor, a servicer, a collection agency, or the current owner. That distinction can affect which records should be matched before payment.
Why A Written Agreement Matters More Than A Verbal Offer
A telephone conversation may start a negotiation, but it does not replace written terms. Before money is sent, the document should identify the account, the total required amount, payment dates, and the effect of completing those payments. Keep the agreement and proof of payment together.
For a current account, compare the full written terms with other available paths rather than choosing from a historical percentage alone. Compare debt relief options or review how a debt settlement program is structured.
Document Review Notes For This Specific Example
Why The $1,200.00 Amount Needs Written Context
The documented figure $1,200.00 has meaning because the letter links it to the account. An amount mentioned without a document cannot replace account-specific language. Before acting on current terms, read the payment sequence together with the condition for completion.
How To Interpret The 79% Label
Within this account summary, 79% compares the two amounts printed above. That label should not become a typical-results statement. A complete cost comparison looks beyond the headline reduction.
Using This Wells Fargo Record In A Broader Comparison
This dated record can establish the figures used in this single example with Wells Fargo. That evidence does not choose the best current approach for another household. The next decision should account for the person’s accounts, budget, credit goals, and available written terms.
A Paper Trail Built Around $5,766.59 And $1,200.00
The account snapshot pairs $5,766.59 against $1,200.00 so the arithmetic is easy to follow. The scanned letter remains the source document. Compare with the cards, then verify with the image.
Questions The the date shown in the letter Letter Can And Cannot Resolve
The preserved letter records the account context, required amount, and any deadlines appearing in the scan. It cannot establish a current creditor policy or reporting result. Check those open questions against current records.
Keeping The Wells Fargo Example Account-Specific
The amounts summarized here $5,766.59, $1,200.00, as well as 79% comes from the same dated record. Reading the figures as one set reduces the risk of implying a typical result. When comparing another letter, match the documents on more than percentage alone.
Reading The the date shown in the letter Figures Together
For this archived account Wells Fargo connects its stated amounts with the date shown in the letter. The balance appears as $5,766.59, with written terms totaling $1,200.00. The gap between those amounts equals $4,566.59; the corresponding balance reduction is 79%.
What The $5,766.59 Balance Establishes
That recorded balance $5,766.59 comes from this one preserved letter. Readers should not treat it as an eligibility rule or expected account size. If a current account has other figures, follow that account’s written terms.
A Step-By-Step Review Of This Archived Letter
1. Locate The Wells Fargo Account Reference
Open the review by confirming the creditor name and masked account digits using records already in your possession. For this archive entry, the relevant creditor label is Wells Fargo and the document date is the date shown in the letter.
2. Reconcile $5,766.59 With $1,200.00
Check the stated balance against the settlement total. This example records $5,766.59 alongside $1,200.00. If installments appear in another offer, add them independently and confirm the sum matches the written total.
3. Find The Deadline Attached To The $1,200.00 Figure
The dollar figure needs a due date. Review the document for the payment date, schedule, and delivery instructions. Do not transfer the schedule from this old letter to a new account.
4. Identify The Completion Language Behind 79%
Look for wording that states the account consequence of paying the agreed total. A headline reduction does not answer this question. For the page summary, 79% describes only the mathematical difference between $5,766.59 and $1,200.00.
5. Preserve Evidence From The the date shown in the letter Record
Save the entire settlement document with transaction records and follow-up correspondence. A partial capture can miss essential language. The page keeps the account figures connected to their source.
6. Separate The Historical Result From A Current Decision
With the archived terms understood, look at today’s account-specific paths. A past agreement cannot establish current eligibility. Compare affordability, total cost, timing, account status, and credit priorities before choosing among repayment, consolidation, debt management, settlement, or another available route.
7. Use The Wells Fargo Letter As Evidence, Not A Promise
The reliable takeaway stays account-specific: the archived agreement contains the figures summarized. It should not be generalized into typical performance. That distinction lets the page remain useful for research without presenting $5,766.59, $1,200.00, or 79% as a prediction.
Comparison Questions Raised By This Letter
Was The $1,200.00 Amount A Lump Sum Or Installments?
That cannot be decided from the summary card. Read the payment paragraph in the the date shown in the letter record rather than assuming a lump sum. For today’s account, compare the complete amount, the time allowed, and what occurs after a missed installment.
Did Wells Fargo Or Another Account Holder Issue The Letter?
The familiar creditor name does not always identify the sender. Verify the issuing party before treating the document as authoritative. Repeat that verification on a current account.
Does The 79% Figure Predict Credit Impact?
A settlement calculation is not a credit-score forecast. Reporting and score effects vary with the full credit profile and account timeline. The 79% label on this page remains limited to the difference between $5,766.59 and $1,200.00.
Could The $5,766.59 Account Create A Tax Question?
A reduction in an account balance may raise a tax issue. The letter itself does not determine the answer. Retain any Form 1099-C and review the applicable IRS instructions.
How Should This the date shown in the letter Example Be Used Today?
Use the archive to recognize important agreement fields, not as a price quote. A current decision should compare all available routes. The fact that the archived amount was $1,200.00 on a $5,766.59 balance does not set terms for another consumer.
What Makes This Wells Fargo Page More Than A Scanned Image?
The page pairs the original image with structured figures and definitions. It supports a careful review instead of asking the reader to infer every point from the scan. The unique combination here is Wells Fargo, the date shown in the letter, $5,766.59, $1,200.00, and 79%.
Other Historical Wells Fargo Letter Examples
This archive contains more than one Wells Fargo document. The table is provided to compare dated records, not to calculate an average or predict a new result.
| Archived Example | Balance In Letter | Settlement Amount | Documented Reduction* |
|---|---|---|---|
| This Letter | $5,766.59 | $1,200.00 | 79% |
| September 2014 | $2,040.90 | $1,020.48 | 50% |
| January 2020 | $12,626.14 | $5,050.46 | 60% |
| February 2008 | $4,957.43 | $2,479.00 | 50% |
*Each percentage compares only the balance and settlement amount shown in that letter. It is not net savings and does not include program fees or possible tax consequences.
Frequently Asked Questions
What does this Wells Fargo settlement letter document?
It records one historical account with a stated balance of $5,766.59 and a settlement amount of $1,200.00. The displayed 79% reduction is calculated from those two figures only.
Is this Wells Fargo letter a current offer?
No. The document is dated the date shown in the letter and belongs to one archived account. It does not state what Wells Fargo or another account owner will offer today.
Is the 79% reduction net savings?
No. It compares the balance and settlement amount in this letter. It does not subtract program fees or account for possible tax consequences, so it should not be described as net savings.
How can I compare this Wells Fargo example with my account?
Use the document to identify terms that should be clear in writing, such as the account, total amount, due dates, and treatment of the remaining balance. Do not use its percentage as an estimate for a different account.
Does the percentage on this page show typical savings?
No. It is calculated only from the balance and settlement amount stated in this one archived letter. It is not a typical-result claim and does not include program fees or possible tax consequences.
Can credit impact be the same for everyone?
No. Credit effects depend on the person's starting profile, account history, reporting, balances, and the option used. A historical letter cannot predict the impact on another person's credit.
What happens if an installment in a settlement agreement is missed?
The answer depends on the written agreement. Some arrangements may be cancelled or changed after a missed payment, so review that clause in advance and obtain any modification in writing.
What should a debt settlement offer letter include?
It should identify the account, state the total amount required, list payment dates or a deadline, and explain how the remaining balance will be treated after the required payment is received.