

Chase Bank Debt Settlement Letter From January 2020
A historical letter cannot predict a new offer, but it can show what details belonged in one completed Chase agreement. The image and figures below preserve the account-specific evidence while the surrounding guidance explains how to read it.
Check Your Debt Relief Options
No cost to check options. No obligation.
Prefer to talk now? Call 1-877-850-3328What This Chase Settlement Letter Documents
This archived record is dated January 2020. It identifies a balance of $10,985.53 and a settlement amount of $3,954.79. The difference between those two stated amounts is displayed as a 65% documented balance reduction.
| Item | What This Letter Shows |
|---|---|
| Creditor Or Account Name | Chase |
| Document Date | January 2020 |
| Balance Stated In Letter | $10,985.53 |
| Settlement Amount In Letter | $3,954.79 |
| Documented Balance Reduction | 65% |
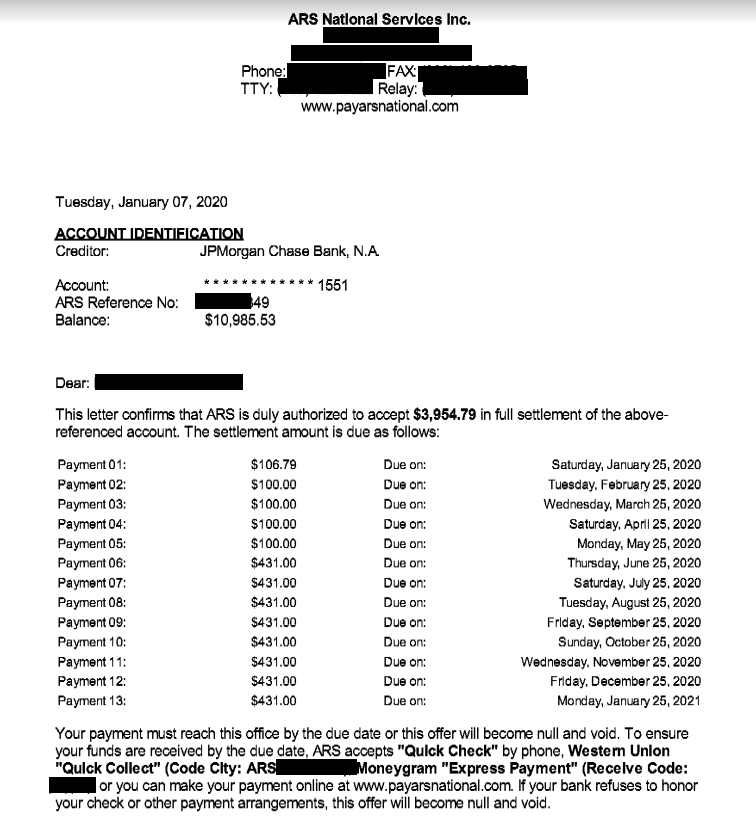
Historical settlement letter kept in the CuraDebt archive. Personal identifying details are redacted for privacy. See more settlement letters.
Calculated only from the balance and settlement amount shown in this letter. This is not net savings and does not include program fees or possible tax consequences.
How To Read This January 2020 Agreement
Start with the account reference and the party sending the letter. Then compare the stated balance of $10,985.53 with the agreed amount of $3,954.79. The 65% figure on this page is a calculation from those two numbers only; it is not a statement of net savings after fees or taxes.
The safest use of a historical example is to learn what should be documented. It should not be used to infer that the same creditor, a collector, or an independent provider will produce the same terms on another account.
A Verification Checklist For This Letter Type
Use the scanned document and the summary together. Before acting on a different agreement, verify each of the following in that agreement's own wording:
- Letter date and offer deadline are both visible
- The balance and agreed amount are not confused
- One payment versus installments is unmistakable
- Instructions can be verified independently
- The completed agreement and receipts can be saved together
When an account has changed hands, confirm whether the sender is the original creditor, a servicer, a collection agency, or the current owner. That distinction can affect which records should be matched before payment.
Settlement Offer Letter, Settlement Request Letter, Or Payoff Statement?
A settlement request is sent by a consumer or representative to ask for terms. A settlement offer or agreement states terms the creditor or collector is prepared to accept. A payoff statement normally reports the amount needed to pay an account in full. The document shown here is useful because it records accepted settlement terms, not merely a request.
For a current account, compare the full written terms with other available paths rather than choosing from a historical percentage alone. Compare debt relief options or review how a debt settlement program is structured.
Document Review Notes For This Specific Example
Questions The January 2020 Letter Can And Cannot Resolve
This document can reveal who issued it, the two financial figures, and the written schedule. The example cannot supply a current creditor policy or reporting result. Verify the unanswered items in the proposed agreement.
Keeping The Chase Example Account-Specific
Every displayed reference to $10,985.53, $3,954.79, plus 65% belongs to one archived account. Reading the figures as one set keeps the evidence separate from predictions. When comparing another letter, compare ownership, timing, payment structure, and final terms.
Reading The January 2020 Figures Together
For the document shown here Chase places the recorded amounts in January 2020. The account amount is recorded as $10,985.53, and the agreed amount is $3,954.79. Subtracting those figures produces $7,030.74; that calculation is summarized as 65%.
What The $10,985.53 Balance Establishes
The number $10,985.53 is specific to the document on this page. Readers should not treat it as a recommended debt level or typical balance. For someone comparing a new offer, follow that account’s written terms.
Why The $3,954.79 Amount Needs Written Context
The letter’s stated total of $3,954.79 can be evaluated because the document supplies context. A number heard by telephone does not establish accepted terms. When reviewing a different proposal, add every required payment and verify the completion language.
How To Interpret The 65% Label
In the displayed example, 65% summarizes the gap between the stated figures. Readers should not convert it into an expected outcome for another account. Evaluating overall cost keeps fees and potential tax treatment separate.
Using This Chase Record In A Broader Comparison
This dated record can establish how this one account was recorded in connection with Chase. It cannot select the best current approach for another household. A sound decision uses the person’s accounts, budget, credit goals, and available written terms.
A Paper Trail Built Around $10,985.53 And $3,954.79
The page highlights $10,985.53 next to $3,954.79 as a concise account summary. The image still controls the wording. Treat the cards as navigation, not as a substitute for the agreement.
A Step-By-Step Review Of This Archived Letter
1. Locate The Chase Account Reference
Begin by matching the named party and account identifier before relying on payment instructions. In the preserved example, the relevant creditor label is Chase and the document date is January 2020.
2. Reconcile $10,985.53 With $3,954.79
Place the two amounts side by side. Here the document begins with $10,985.53 before showing $3,954.79. Where the current proposal is not a lump sum, add them independently and confirm the sum matches the written total.
3. Find The Deadline Attached To The $3,954.79 Figure
A settlement total must be read with its deadline. Use the image to identify each due date and the required payment method. Do not transfer the schedule from this old letter to a new account.
4. Identify The Completion Language Behind 65%
Look for wording that states how the remaining balance is treated upon completion. This clause carries more practical value than a standalone percentage. For the page summary, 65% describes only the mathematical difference between $10,985.53 and $3,954.79.
5. Preserve Evidence From The January 2020 Record
Store the letter with the account file together with receipts and bank confirmations. One cropped image may leave out conditions. The page keeps the account figures connected to their source.
6. Separate The Historical Result From A Current Decision
After reading the letter, look at today’s account-specific paths. This historical record does not forecast a new offer. Compare affordability, total cost, timing, account status, and credit priorities before choosing among repayment, consolidation, debt management, settlement, or another available route.
7. Use The Chase Letter As Evidence, Not A Promise
The evidence should be framed precisely: the scanned letter preserves one completed set of terms. It should not be generalized into typical performance. That distinction lets the page remain useful for research without presenting $10,985.53, $3,954.79, or 65% as a prediction.
Comparison Questions Raised By This Letter
Was The $3,954.79 Amount A Lump Sum Or Installments?
The total alone does not answer that question. Check every dated obligation in the January 2020 agreement. For today’s account, compare the complete amount, the time allowed, and what occurs after a missed installment.
Did Chase Or Another Account Holder Issue The Letter?
Ownership and servicing can change after delinquency. Verify the issuing party before treating the document as authoritative. A new agreement should be checked the same way.
Does The 65% Figure Predict Credit Impact?
A settlement calculation is not a credit-score forecast. Starting credit condition, account status, and subsequent updates can produce different outcomes. The 65% label on this page remains limited to the difference between $10,985.53 and $3,954.79.
Could The $10,985.53 Account Create A Tax Question?
A reduction in an account balance may raise a tax issue. The letter itself does not determine the answer. Save tax correspondence and ask a qualified tax professional about the specific facts.
How Should This January 2020 Example Be Used Today?
Let it illustrate what a paper trail can contain, without treating it as a present offer. Any new plan should be evaluated with up-to-date records. The fact that the archived amount was $3,954.79 on a $10,985.53 balance does not set terms for another consumer.
What Makes This Chase Page More Than A Scanned Image?
The page pairs the original image with structured figures and definitions. It lets the image remain primary while making its key data easier to understand. The unique combination here is Chase, January 2020, $10,985.53, $3,954.79, and 65%.
Other Historical Chase Letter Examples
This archive contains more than one Chase document. The table is provided to compare dated records, not to calculate an average or predict a new result.
| Archived Example | Balance In Letter | Settlement Amount | Documented Reduction* |
|---|---|---|---|
| This Letter | $10,985.53 | $3,954.79 | 65% |
| September 2022 | $6,464.11 | $1,745.31 | 73% |
| August 2014 | $4,854.12 | $1,800.00 | 63% |
| April 2005 | $40,254.57 | $18,114.56 | 55% |
*Each percentage compares only the balance and settlement amount shown in that letter. It is not net savings and does not include program fees or possible tax consequences.
Frequently Asked Questions
What does this Chase settlement letter document?
It records one historical account with a stated balance of $10,985.53 and a settlement amount of $3,954.79. The displayed 65% reduction is calculated from those two figures only.
Is this Chase letter a current offer?
No. The document is dated January 2020 and belongs to one archived account. It does not state what Chase or another account owner will offer today.
Is the 65% reduction net savings?
No. It compares the balance and settlement amount in this letter. It does not subtract program fees or account for possible tax consequences, so it should not be described as net savings.
How can I compare this Chase example with my account?
Use the document to identify terms that should be clear in writing, such as the account, total amount, due dates, and treatment of the remaining balance. Do not use its percentage as an estimate for a different account.
How long should settlement records be kept?
Keep the agreement, payment confirmations, and later account correspondence together. Retention needs can depend on the account and applicable law, so do not discard the documents immediately after payment.
Can a historical settlement letter predict a current offer?
No. Account status, ownership, balance, available funds, creditor policy, and timing can all change. The letter is evidence of one documented account outcome, not a current quote or forecast.
How can the sender of a settlement letter be verified?
Use a trusted statement, the creditor's official website, or another independently verified source to confirm contact information. Do not rely only on details in an unexpected message before sending funds.
What should be checked after the final settlement payment?
Keep proof of payment and compare later account records with the written terms. If a balance or status appears inconsistent, use the agreement and receipts when requesting a review or correction.
