

Chase Bank Debt Settlement Letter From September 2022
Rather than estimating what Chase might do today, this page explains exactly what is visible in one dated agreement. The image and figures below preserve the account-specific evidence while the surrounding guidance explains how to read it.
Check Your Debt Relief Options
No cost to check options. No obligation.
Prefer to talk now? Call 1-877-850-3328What This Chase Settlement Letter Documents
This archived record is dated September 2022. It identifies a balance of $6,464.11 and a settlement amount of $1,745.31. The difference between those two stated amounts is displayed as a 73% documented balance reduction.
| Item | What This Letter Shows |
|---|---|
| Creditor Or Account Name | Chase |
| Document Date | September 2022 |
| Balance Stated In Letter | $6,464.11 |
| Settlement Amount In Letter | $1,745.31 |
| Documented Balance Reduction | 73% |
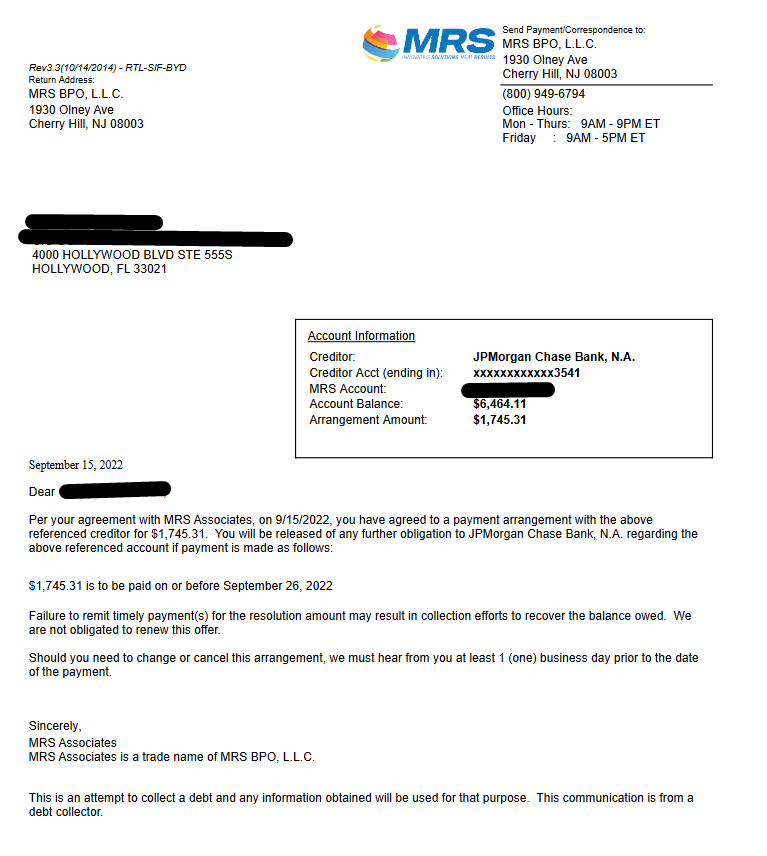
Historical settlement letter kept in the CuraDebt archive. Personal identifying details are redacted for privacy. See more settlement letters.
Calculated only from the balance and settlement amount shown in this letter. This is not net savings and does not include program fees or possible tax consequences.
How To Read This September 2022 Agreement
Check whether the document uses one payment or several, and whether missing a due date changes the arrangement. The historical figures shown here are $6,464.11 and $1,745.31; the letter image remains the controlling source for the exact wording of this example.
The safest use of a historical example is to learn what should be documented. It should not be used to infer that the same creditor, a collector, or an independent provider will produce the same terms on another account.
A Verification Checklist For This Letter Type
Use the scanned document and the summary together. Before acting on a different agreement, verify each of the following in that agreement's own wording:
- The agreement concerns the intended account
- The amount accepted is not merely a temporary payment
- A missed-payment clause is reviewed if present
- The remaining-balance wording is clear
- Proof of each payment will be retained
When an account has changed hands, confirm whether the sender is the original creditor, a servicer, a collection agency, or the current owner. That distinction can affect which records should be matched before payment.
What A Settlement Confirmation Should Let You Prove
A useful confirmation should help establish which account was addressed, what amount was required, when it had to be paid, and how the remaining balance would be treated. The letter and the payment record should be retained together in case the account is later reported inconsistently.
For a current account, compare the full written terms with other available paths rather than choosing from a historical percentage alone. Compare debt relief options or review how a debt settlement program is structured.
Document Review Notes For This Specific Example
Keeping The Chase Example Account-Specific
Every displayed reference to $6,464.11, $1,745.31, plus 73% belongs to one archived account. Preserving their common context prevents an old example from sounding like a quote. If two records are reviewed side by side, match the documents on more than percentage alone.
Reading The September 2022 Figures Together
Within this preserved example Chase dates the account terms to September 2022. The account amount is recorded as $6,464.11, and the agreed amount is $1,745.31. Their arithmetic difference comes to $4,718.80; the displayed reduction is 73%.
What The $6,464.11 Balance Establishes
This opening figure $6,464.11 is specific to the document on this page. Readers should not treat it as a recommended debt level or typical balance. If a current account has other figures, verify the current record independently.
Why The $1,745.31 Amount Needs Written Context
The letter’s stated total of $1,745.31 is useful because it appears with written account terms. A verbal quote leaves the essential conditions unconfirmed. With a present-day account, add every required payment and verify the completion language.
How To Interpret The 73% Label
Within this account summary, 73% is a balance-to-settlement calculation. The percentage does not provide a promise about current settlement terms. Reviewing the economics of a current option also considers provider fees and possible tax consequences.
Using This Chase Record In A Broader Comparison
The archived image can demonstrate how this one account was recorded in connection with Chase. It cannot select settlement, consolidation, debt management, or direct repayment. That comparison needs the full debt mix, payment capacity, account status, priorities, and written costs.
A Paper Trail Built Around $6,464.11 And $1,745.31
The account snapshot pairs $6,464.11 with $1,745.31 as a concise account summary. The image still controls the wording. Treat the cards as navigation, not as a substitute for the agreement.
Questions The September 2022 Letter Can And Cannot Resolve
This document can reveal who issued it, the two financial figures, and the written schedule. The example cannot supply today’s offer range or a new account outcome. Verify the unanswered items in the proposed agreement.
A Step-By-Step Review Of This Archived Letter
1. Locate The Chase Account Reference
Open the review by confirming the creditor name and masked account digits before relying on payment instructions. In the preserved example, the relevant creditor label is Chase and the document date is September 2022.
2. Reconcile $6,464.11 With $1,745.31
Read the opening and accepted figures together. The scanned letter identifies $6,464.11 and pairs it with $1,745.31. When a new agreement uses several payments, add them independently and confirm the sum matches the written total.
3. Find The Deadline Attached To The $1,745.31 Figure
Payment terms require both amount and timing. Check the scanned agreement for when and how the stated amount must be received. Do not transfer the schedule from this old letter to a new account.
4. Identify The Completion Language Behind 73%
The document should make clear what happens after every required payment clears. A headline reduction does not answer this question. For the page summary, 73% describes only the mathematical difference between $6,464.11 and $1,745.31.
5. Preserve Evidence From The September 2022 Record
Store the letter with the account file beside proof of every required payment. A partial capture can miss essential language. The dated letter illustrates the value of written evidence.
6. Separate The Historical Result From A Current Decision
Once the document review is complete, look at today’s account-specific paths. The September 2022 example does not quote today’s account. Compare affordability, total cost, timing, account status, and credit priorities before choosing among repayment, consolidation, debt management, settlement, or another available route.
7. Use The Chase Letter As Evidence, Not A Promise
The evidence should be framed precisely: the scanned letter preserves one completed set of terms. It cannot demonstrate an average outcome. That distinction lets the page remain useful for research without presenting $6,464.11, $1,745.31, or 73% as a prediction.
Comparison Questions Raised By This Letter
Was The $1,745.31 Amount A Lump Sum Or Installments?
The total alone does not answer that question. Check every dated obligation in the September 2022 agreement. If new terms are offered, compare the complete amount, the time allowed, and what occurs after a missed installment.
Did Chase Or Another Account Holder Issue The Letter?
The familiar creditor name does not always identify the sender. Verify the issuing party before treating the document as authoritative. Repeat that verification on a current account.
Does The 73% Figure Predict Credit Impact?
The document’s arithmetic cannot predict reporting impact. Starting credit condition, account status, and subsequent updates can produce different outcomes. The 73% label on this page remains limited to the difference between $6,464.11 and $1,745.31.
Could The $6,464.11 Account Create A Tax Question?
A reduction in an account balance may raise a tax issue. This archive page cannot establish a person’s tax treatment. Save tax correspondence and ask a qualified tax professional about the specific facts.
How Should This September 2022 Example Be Used Today?
Use it as a checklist for written terms, not as a price quote. A current decision should compare all available routes. The fact that the archived amount was $1,745.31 on a $6,464.11 balance does not set terms for another consumer.
What Makes This Chase Page More Than A Scanned Image?
The supporting text separates document facts from broader settlement questions. That helps a reader verify what is present before comparing options. The unique combination here is Chase, September 2022, $6,464.11, $1,745.31, and 73%.
Other Historical Chase Letter Examples
This archive contains more than one Chase document. The table is provided to compare dated records, not to calculate an average or predict a new result.
| Archived Example | Balance In Letter | Settlement Amount | Documented Reduction* |
|---|---|---|---|
| This Letter | $6,464.11 | $1,745.31 | 73% |
| August 2014 | $4,854.12 | $1,800.00 | 63% |
| April 2005 | $40,254.57 | $18,114.56 | 55% |
| January 2002 | $2,039 | $612 | 70% |
*Each percentage compares only the balance and settlement amount shown in that letter. It is not net savings and does not include program fees or possible tax consequences.
Frequently Asked Questions
What does this Chase settlement letter document?
It records one historical account with a stated balance of $6,464.11 and a settlement amount of $1,745.31. The displayed 73% reduction is calculated from those two figures only.
Is this Chase letter a current offer?
No. The document is dated September 2022 and belongs to one archived account. It does not state what Chase or another account owner will offer today.
Is the 73% reduction net savings?
No. It compares the balance and settlement amount in this letter. It does not subtract program fees or account for possible tax consequences, so it should not be described as net savings.
How can I compare this Chase example with my account?
Use the document to identify terms that should be clear in writing, such as the account, total amount, due dates, and treatment of the remaining balance. Do not use its percentage as an estimate for a different account.
What happens if an installment in a settlement agreement is missed?
The answer depends on the written agreement. Some arrangements may be cancelled or changed after a missed payment, so review that clause in advance and obtain any modification in writing.
What should a debt settlement offer letter include?
It should identify the account, state the total amount required, list payment dates or a deadline, and explain how the remaining balance will be treated after the required payment is received.
Can a historical settlement letter predict a current offer?
No. Account status, ownership, balance, available funds, creditor policy, and timing can all change. The letter is evidence of one documented account outcome, not a current quote or forecast.
Is a payoff statement the same as a settlement letter?
Usually not. A payoff statement generally shows the amount needed to pay an account in full. A settlement letter may document acceptance of less than the stated balance under specific conditions.
