

HSBC Debt Settlement Letter July 2009
This page focuses on the document itself: what one HSBC letter stated, what the numbers mean, and what a reader should verify in a different agreement. The image and figures below preserve the account-specific evidence while the surrounding guidance explains how to read it.
Check Your Debt Relief Options
No cost to check options. No obligation.
Prefer to talk now? Call 1-877-850-3328What This HSBC Settlement Letter Documents
This archived record is dated July 2009. It identifies a balance of $8,851.87 and a settlement amount of $1,770.00. The difference between those two stated amounts is displayed as a 80% documented balance reduction.
| Item | What This Letter Shows |
|---|---|
| Creditor Or Account Name | HSBC |
| Document Date | July 2009 |
| Balance Stated In Letter | $8,851.87 |
| Settlement Amount In Letter | $1,770.00 |
| Documented Balance Reduction | 80% |
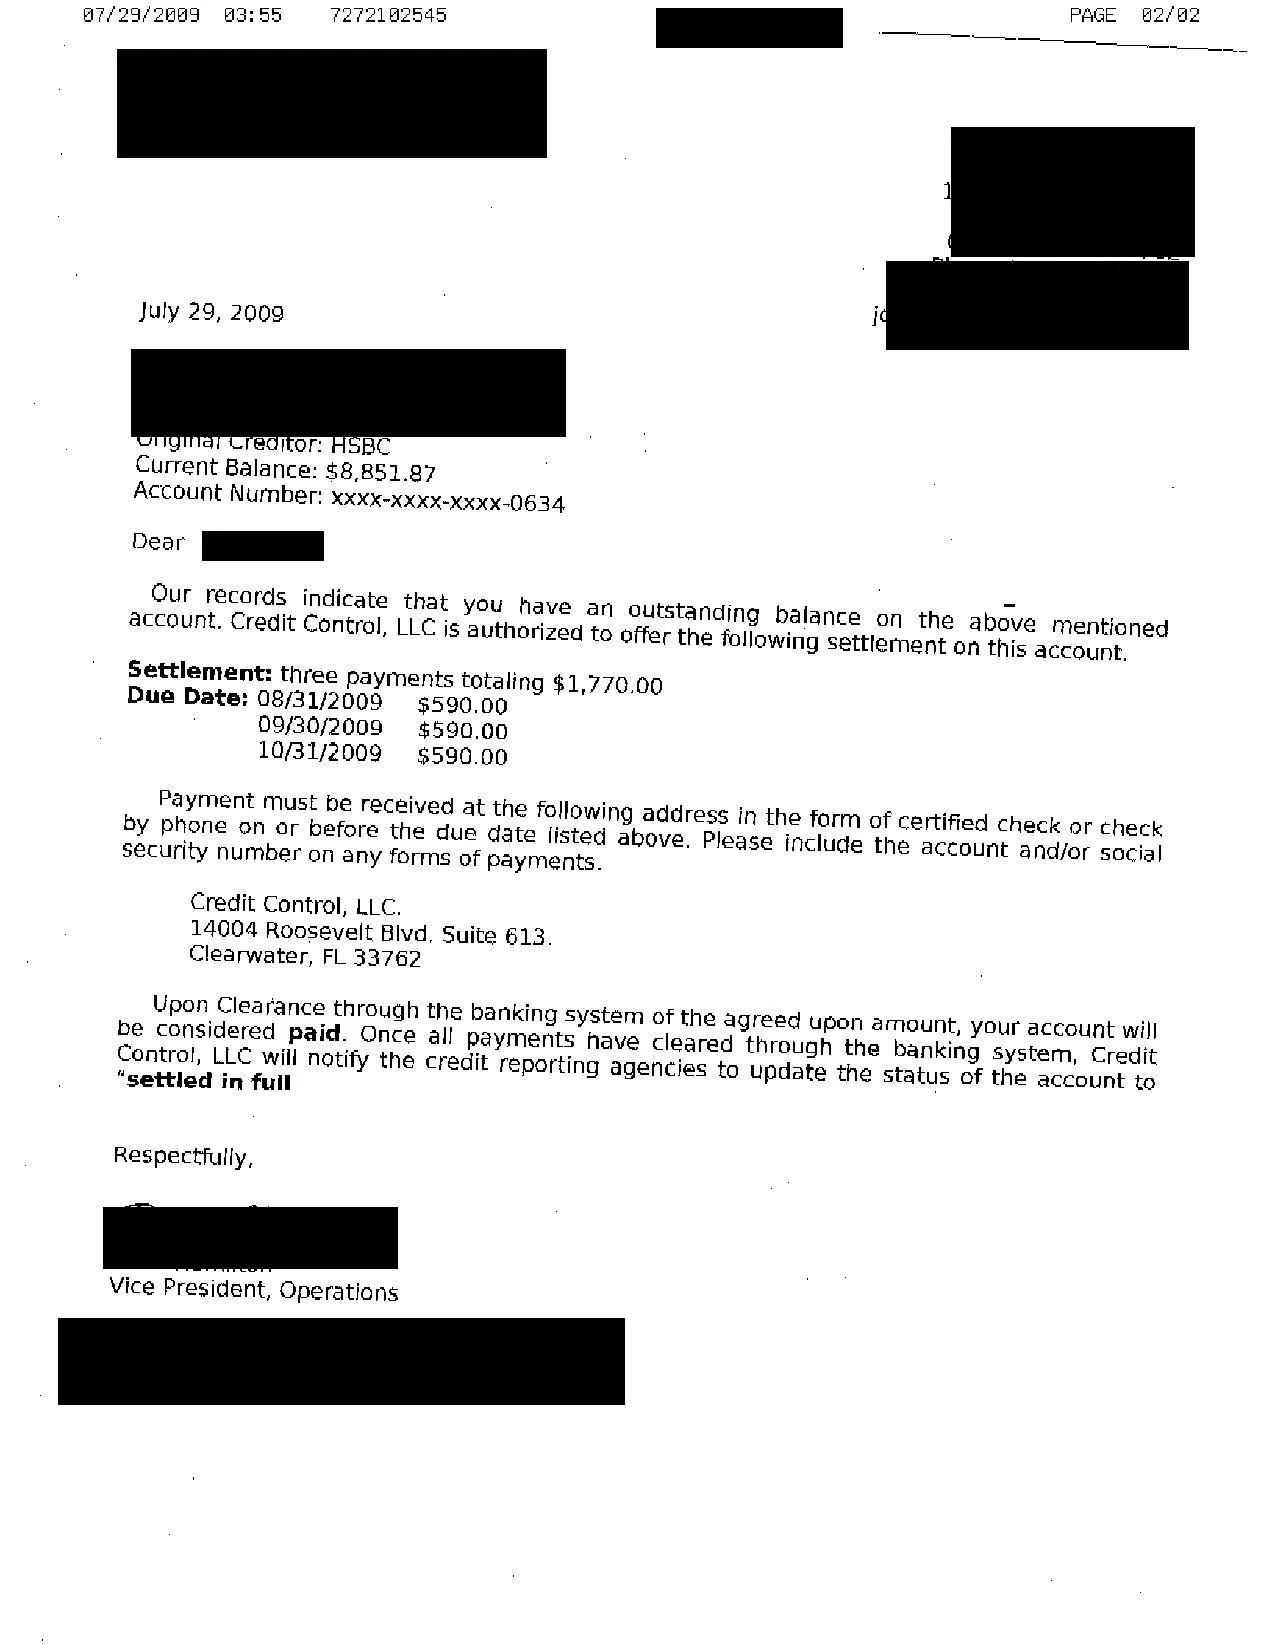
Historical settlement letter kept in the CuraDebt archive. Personal identifying details are redacted for privacy. See more settlement letters.
Calculated only from the balance and settlement amount shown in this letter. This is not net savings and does not include program fees or possible tax consequences.
How To Read This July 2009 Agreement
Check whether the document uses one payment or several, and whether missing a due date changes the arrangement. The historical figures shown here are $8,851.87 and $1,770.00; the letter image remains the controlling source for the exact wording of this example.
The safest use of a historical example is to learn what should be documented. It should not be used to infer that the same creditor, a collector, or an independent provider will produce the same terms on another account.
A Verification Checklist For This Letter Type
Use the scanned document and the summary together. Before acting on a different agreement, verify each of the following in that agreement's own wording:
- Letter date and offer deadline are both visible
- The balance and agreed amount are not confused
- One payment versus installments is unmistakable
- Instructions can be verified independently
- The completed agreement and receipts can be saved together
When an account has changed hands, confirm whether the sender is the original creditor, a servicer, a collection agency, or the current owner. That distinction can affect which records should be matched before payment.
Why The Date On A Settlement Letter Matters
Creditor policies, account ownership, and collection status can change. A letter dated July 2009 shows what was documented for one account at that time. It does not establish a standing policy or a current offer for someone else.
For a current account, compare the full written terms with other available paths rather than choosing from a historical percentage alone. Compare debt relief options or review how a debt settlement program is structured.
Document Review Notes For This Specific Example
What The $8,851.87 Balance Establishes
This opening figure $8,851.87 belongs only to the archived account. Nothing on the page makes it an eligibility rule or expected account size. For a different account, base the comparison on the current documents.
Why The $1,770.00 Amount Needs Written Context
The letter’s stated total of $1,770.00 is useful because it appears with written account terms. A number heard by telephone does not establish accepted terms. When reviewing a different proposal, match the total to its deadlines and remaining-balance wording.
How To Interpret The 80% Label
In the displayed example, 80% compares the two amounts printed above. Readers should not convert it into a forecast, average, or net-savings claim. Evaluating overall cost looks beyond the headline reduction.
Using This HSBC Record In A Broader Comparison
This dated record can establish whether these particular terms existed with HSBC. The letter cannot rank settlement, consolidation, debt management, or direct repayment. That comparison needs the person’s accounts, budget, credit goals, and available written terms.
A Paper Trail Built Around $8,851.87 And $1,770.00
The page highlights $8,851.87 with $1,770.00 to make the two stated amounts scannable. The complete document supplies the operative language. Compare with the cards, then verify with the image.
Questions The July 2009 Letter Can And Cannot Resolve
The preserved letter records the creditor, balance, settlement figure, and stated conditions. It cannot establish a guarantee about timing, acceptance, or credit effects. Use current statements and written terms for everything the archive cannot answer.
Keeping The HSBC Example Account-Specific
The three figures $8,851.87, $1,770.00, together with 80% comes from the same dated record. Keeping them together avoids turning history into a general promise. For a second archived example, review the account type, written total, deadlines, and disposition wording.
Reading The July 2009 Figures Together
For this archived account HSBC connects its stated amounts with July 2009. The account amount is recorded as $8,851.87, with written terms totaling $1,770.00. Their arithmetic difference comes to $7,081.87; the page expresses that difference as 80%.
A Step-By-Step Review Of This Archived Letter
1. Locate The HSBC Account Reference
Start with the creditor name and masked account digits using records already in your possession. For this archive entry, the relevant creditor label is HSBC and the document date is July 2009.
2. Reconcile $8,851.87 With $1,770.00
Trace the account amount to the agreed payment. The account summary lists $8,851.87 before showing $1,770.00. When a new agreement uses several payments, add them independently and confirm the sum matches the written total.
3. Find The Deadline Attached To The $1,770.00 Figure
An accepted amount is incomplete without timing. Use the image to identify the deadline plus any installment sequence. Do not transfer the schedule from this old letter to a new account.
4. Identify The Completion Language Behind 80%
The key clause explains how the remaining balance is treated upon completion. The percentage cannot replace this condition. For the page summary, 80% describes only the mathematical difference between $8,851.87 and $1,770.00.
5. Preserve Evidence From The July 2009 Record
Keep a complete copy of the agreement together with receipts and bank confirmations. One cropped image may leave out conditions. The dated letter illustrates the value of written evidence.
6. Separate The Historical Result From A Current Decision
With the archived terms understood, return to the choices available now. The July 2009 example does not quote today’s account. Compare affordability, total cost, timing, account status, and credit priorities before choosing among repayment, consolidation, debt management, settlement, or another available route.
7. Use The HSBC Letter As Evidence, Not A Promise
The reliable takeaway stays account-specific: this dated record documents the shown balance and settlement amount. It does not establish what most consumers receive. That distinction lets the page remain useful for research without presenting $8,851.87, $1,770.00, or 80% as a prediction.
Comparison Questions Raised By This Letter
Was The $1,770.00 Amount A Lump Sum Or Installments?
The total alone does not answer that question. Inspect the July 2009 image for one due date or a sequence of dates. For today’s account, compare the complete amount, the time allowed, and what occurs after a missed installment.
Did HSBC Or Another Account Holder Issue The Letter?
The brand associated with a debt may differ from the current owner. Compare the letterhead and account reference with trusted records. Use the same ownership check for any present offer.
Does The 80% Figure Predict Credit Impact?
A settlement calculation is not a credit-score forecast. Credit outcomes depend on the starting file, account history, balances, and reporting. The 80% label on this page remains limited to the difference between $8,851.87 and $1,770.00.
Could The $8,851.87 Account Create A Tax Question?
Canceled debt can have tax consequences in some circumstances. The settlement document is not a substitute for tax guidance. Include any cancellation-of-debt form when obtaining account-specific tax advice.
How Should This July 2009 Example Be Used Today?
Let it illustrate what a paper trail can contain, without treating it as a present offer. A current decision should compare all available routes. The fact that the archived amount was $1,770.00 on a $8,851.87 balance does not set terms for another consumer.
What Makes This HSBC Page More Than A Scanned Image?
The layout makes the creditor, date, amounts, and limitations independently scannable. That helps a reader verify what is present before comparing options. The unique combination here is HSBC, July 2009, $8,851.87, $1,770.00, and 80%.
Other Historical HSBC Letter Examples
This archive contains more than one HSBC document. The table is provided to compare dated records, not to calculate an average or predict a new result.
| Archived Example | Balance In Letter | Settlement Amount | Documented Reduction* |
|---|---|---|---|
| This Letter | $8,851.87 | $1,770.00 | 80% |
| March 2008 | $3,813.38 | $1,715.00 | 56% |
*Each percentage compares only the balance and settlement amount shown in that letter. It is not net savings and does not include program fees or possible tax consequences.
Frequently Asked Questions
What does this HSBC settlement letter document?
It records one historical account with a stated balance of $8,851.87 and a settlement amount of $1,770.00. The displayed 80% reduction is calculated from those two figures only.
Is this HSBC letter a current offer?
No. The document is dated July 2009 and belongs to one archived account. It does not state what HSBC or another account owner will offer today.
Is the 80% reduction net savings?
No. It compares the balance and settlement amount in this letter. It does not subtract program fees or account for possible tax consequences, so it should not be described as net savings.
How can I compare this HSBC example with my account?
Use the document to identify terms that should be clear in writing, such as the account, total amount, due dates, and treatment of the remaining balance. Do not use its percentage as an estimate for a different account.
What should be checked after the final settlement payment?
Keep proof of payment and compare later account records with the written terms. If a balance or status appears inconsistent, use the agreement and receipts when requesting a review or correction.
Should payment be sent before the agreement is in writing?
Written terms should be obtained and reviewed before payment. Confirm the sender, account, total amount, due dates, and treatment of the remaining balance, then keep the agreement with every payment record.
Why are personal details removed from the displayed letter?
Names, addresses, and account details are redacted to protect privacy. The creditor name and financial terms needed to understand the historical example remain visible.
How long should settlement records be kept?
Keep the agreement, payment confirmations, and later account correspondence together. Retention needs can depend on the account and applicable law, so do not discard the documents immediately after payment.