
LVNV Funding Debt Settlement Letter From March 2024

This March 22, 2024 LVNV Funding letter offered six payments of $263, totaling $1,578, on a stated $2,867.71 balance. It documents the offer and schedule, not proof that every payment cleared. Use it to check written terms, not predict your own discount. You can also request a free, no-obligation options review.
The numbers
$2,867.71 stated balance; six offered payments of $263 total $1,578. The $1,289.71 difference is about 45%, before fees or possible taxes.
How it worked
The March 22, 2024 letter sets payment dates from March 31 through August 31, 2024. This archived offer is not a current payment instruction or a receipt.
What to expect
Another account may receive different terms or no settlement offer. Compare the complete payment obligation and any separately paid fees, not a percentage alone.
The letter
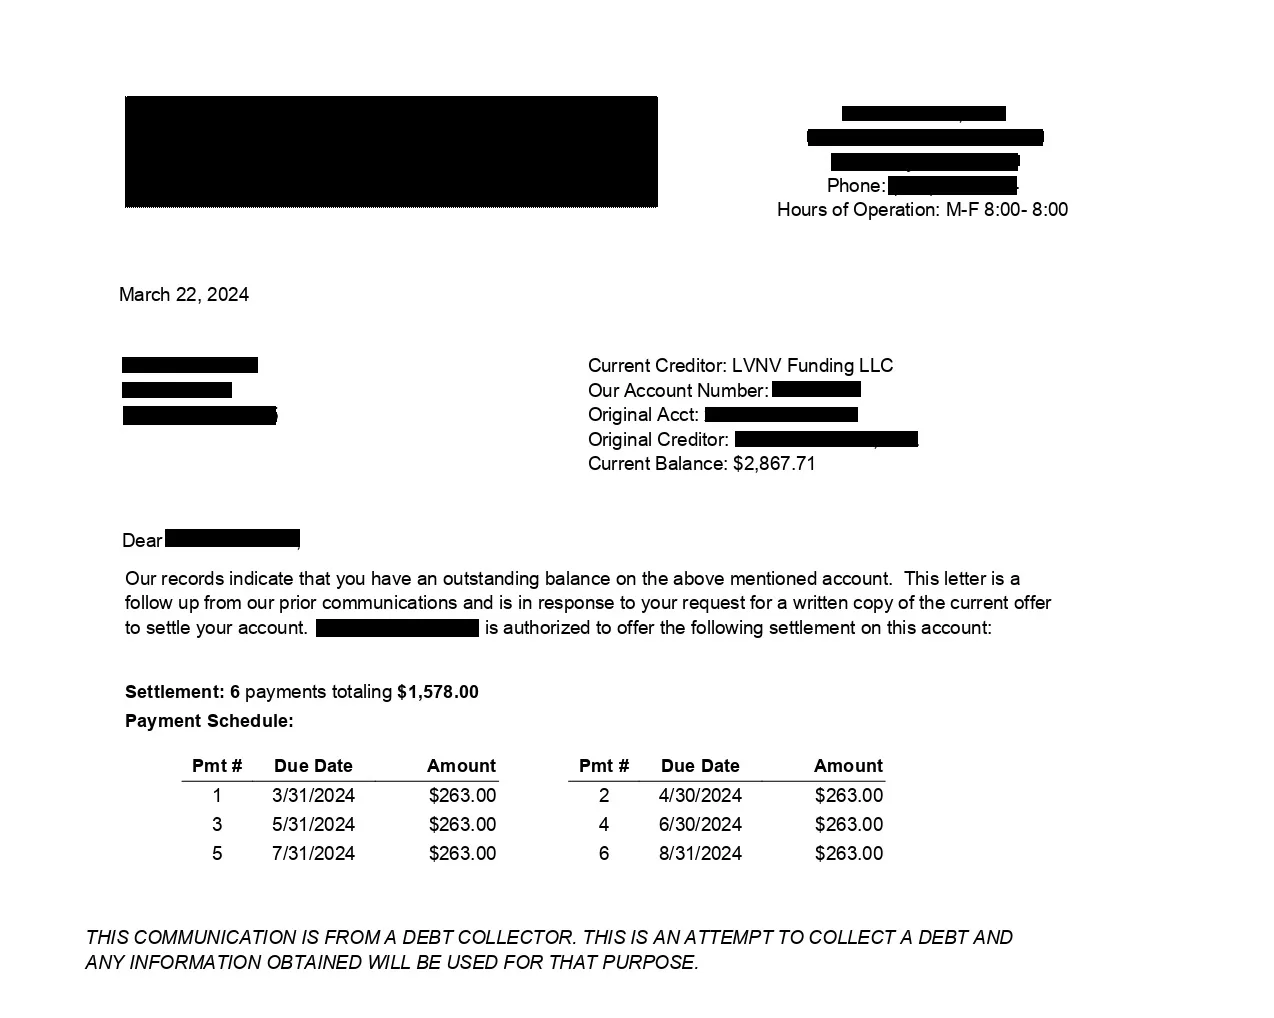
Archived March 22, 2024 settlement offer. Personal identifying details are redacted. The image is not proof of payment completion. See more settlement letters
Who Owns The Account And Who Services It?
LVNV Funding buys debt and says it outsources account management to Resurgent Capital Services. A servicer is not necessarily the debt owner. Check your own current notice before using payment instructions. A purchase price or another person's debt negotiation does not establish what your account will settle for. See LVNV Funding's account-management explanation.
Verify First, Then Protect the Statute Clock
Confirm the account and collector before payment. For covered consumer-debt collection, a written dispute sent within the validation period generally requires collection of the disputed debt to pause until verification is sent. Read the deadline on your notice; it is not simply 30 days from any phone call. Old-debt limitation rules depend on state law, and a payment or acknowledgment can have consequences. A settlement discussion does not extend a court deadline. Consult a licensed attorney about a lawsuit or time-barred debt. Review the CFPB validation-notice guidance before comparing a debt settlement program.
Check The Payment Total Before Comparing Offers
In this letter, 6 × $263 = $1,578. Subtracting that total from $2,867.71 gives $1,289.71, but that is a balance difference, not verified net savings. For a current proposal, add any provider or account fees paid separately; do not add a fee twice if it is already included in the quoted total. Keep possible tax consequences separate until reviewed.
Compare the total, every due date, what happens after a missed payment and the wording about the remaining balance. A smaller total is not affordable if the schedule leaves too little for essential expenses. Do not deliberately miss payments to pursue a discount. The CFPB settlement checklist explains how to assess an affordable proposal and obtain written terms.
Frequently Asked Questions
What is LVNV Funding LLC?
LVNV Funding is a debt buyer. Its website identifies Resurgent Capital Services as the company managing its accounts. Confirm the owner and authorized servicer on your own current account notice.
Why would LVNV Funding settle for less?
An account owner may consider a reduced payment, but no purchase price or historical example guarantees an offer. The terms depend on the account and the owner's decision.
Is this LVNV Funding settlement letter real?
The redacted archive image is dated March 22, 2024. It shows a $2,867.71 balance and an offer of six $263 payments, totaling $1,578. It does not prove all payments cleared.
Should I validate an LVNV debt before paying?
Verify the account, current owner and collector before paying. Use the validation notice to identify your dispute rights and deadline. A debt's age and whether a lawsuit is permitted are separate legal questions; obtain legal advice where needed.
Is a debt settlement letter legally binding?
Enforceability depends on the terms, acceptance and applicable law, not merely whether a document has a signature. Obtain clear written terms before paying. A licensed attorney can review a disputed agreement.
Can I still settle after being sued?
Settlement may remain possible during a lawsuit, but neither an offer nor negotiations stop court deadlines automatically. Respond as required by the court and consult a licensed attorney. No settlement outcome is guaranteed.
Is this settlement letter real?
The page displays a redacted historical offer, with the balance and payment schedule visible. The document alone is not a receipt or proof of a completed settlement.
What happens after I make the final settlement payment?
Keep the agreement and payment confirmations, and request written confirmation of the account's disposition. Compare later account and credit-report information with the agreed terms. Reporting timing varies; dispute inaccurate information with supporting records rather than relying on a fixed update deadline.
Can I settle directly with the original creditor, or only with a collection agency?
The original creditor, debt buyer and collection servicer can have different roles. Confirm who owns the account and who is authorized to accept payment. Do not assume every collection agency owns the debt.
How do I verify a debt before I settle it?
Read the validation notice and its stated dispute deadline. A timely written dispute of covered consumer debt generally pauses collection of the disputed debt until verification is sent. Keep a copy and proof of delivery. Verification does not by itself resolve a statute-of-limitations defense or extend a court deadline.
Is it better to settle in a lump sum or a payment plan?
Neither structure is automatically better. Compare the complete total, dates and missed-payment terms against an affordable budget. This historical letter offered six installments; it does not establish that a lump sum would have been cheaper.
What happens if I miss a payment in a settlement plan?
The consequences depend on the written terms. A missed payment may cancel or change a settlement. Ask about any problem before the deadline and obtain a written modification; do not assume a grace period exists.
How do I find out what my LVNV account could settle for?
You can request a free, no-obligation evaluation using your approximate debt amount. CuraDebt provides referral and matching, not negotiation or a guaranteed settlement quote. Compare any independent provider's written fees, services and terms with other available options.
Related Resources
- How the debt settlement program works
- See more real settlement letters
- Compare all your debt relief options
- How debt negotiation works
- FMA Alliance Ltd. Debt Settlement Letter From March 2008
- KeyBank Debt Settlement Letter From March 2019
- Sallie Mae Student Loan Settlement Letter From March 2015
- USAA Savings Bank Debt Settlement Letter From March 2014